

Can You Transfer Your NHS Pension to a SIPP?
For almost everyone, no. NHS Pensions have not allowed transfers to SIPPs or personal pensions since April 2015. Why the rule exists, the one narrow exception, where an NHS pension can go, and what doctors who want a SIPP do instead.
The short answer
| Your situation | Can you transfer to a SIPP? |
|---|---|
| Two or more years' qualifying membership | No. Not permitted since 6 April 2015 |
| Less than two years' membership, and you have left | Possibly, within strict time limits |
| Still working in the NHS and paying in | No. No transfer of any kind while you are in pensionable NHS work |
Most doctors asking this question have years of membership, so the practical answer is no. What you can do is keep the NHS pension and pay into a SIPP as well, or stop paying into the NHS scheme and save into a SIPP from now on. Both are covered below.
Why the NHS pension cannot be moved
The NHS Pension Scheme is unfunded. There is no invested pot with your name on it. Pensions are paid from the contributions coming in and from public money as they fall due.
When pension freedoms arrived in April 2015, letting people with defined contribution pots draw them as cash, the government closed the route from unfunded public service schemes into those pots. The Pension Schemes Act 2015 stopped transfers from unfunded defined benefit schemes to any scheme offering flexible benefits. Otherwise a wave of transfers would have turned future pension promises into immediate cash payments from public funds.
So the rule is not peculiar to the NHS. The same applies to the other unfunded public service schemes, such as the teachers' and civil service schemes.
The one exception: less than two years' membership
If you have less than two years' qualifying membership, NHS Pensions will consider a transfer to a personal pension or SIPP, but only if you:
- take out the personal pension within 12 months of leaving pensionable NHS employment,
- apply for the transfer within 12 months of taking it out, and
- complete the transfer before your normal pension age.
If the transfer value is over £30,000, you must also send signed confirmation from an independent financial adviser that you have had appropriate advice.
This mostly affects people who joined the NHS briefly. A GP who trained and worked in the NHS will almost always have more than two years.
Where an NHS pension can be transferred
With two or more years' membership, you can transfer to:
- another registered defined benefit pension scheme, or
- a scheme in the Public Sector Transfer Club, a group of mainly public sector schemes that exchange transfers on terms that broadly keep your years of service.
Either way, the transfer must be completed before your normal pension age, and you must have left NHS pensionable employment first. While you are still working in the NHS and paying in, NHS Pensions can give you only an estimate of the transfer value, not a guaranteed figure.
Transfers out of the NHS scheme are rare for doctors, not least because most defined benefit schemes outside the public sector are closed to new members.
What you can do instead
Pay into a SIPP as well
Nothing stops you having a SIPP alongside the NHS pension. Contributions get tax relief, with basic rate relief added to the SIPP and higher rate relief claimed through your tax return.
The limit is the annual allowance: £60,000 for most people, tapered down for the highest earners, with unused allowance carried forward from the last three years. Your NHS pension growth counts towards it as well as what you pay into the SIPP, and for GPs that growth can be large in a good year. Check your position with the annual allowance calculator before making big SIPP contributions.
Stop paying into the NHS scheme and save into a SIPP
You can opt out of the NHS scheme and put your own money into a SIPP from then on. This is not a transfer:
- What you have already built stays in the NHS scheme as a deferred pension, increased each year in line with inflation and paid from your normal pension age.
- Only future saving goes into the SIPP.
- You give up the scheme's other benefits while you are out: the death in service lump sum of twice your pay, the survivor's pension, ill health retirement, and any employer contribution paid for you. For salaried and locum GPs that employer contribution does not follow you into the SIPP.
Whether that trade can ever pay off depends on your pay, your working arrangement and the investment return you assume. The NHS pension vs SIPP calculator works out the return a SIPP would need to match the NHS pension, and the NHS vs SIPP guide explains what each side includes.
Leave the NHS pension where it is
If you leave the NHS, your benefits stay in the scheme until you claim them. There is no need to move them to get them paid, and you can take them from age 55 with a reduction for early payment, or in full at your normal pension age.
Free to start — on iPhone, Android and the web
Pensioning locum sessions?
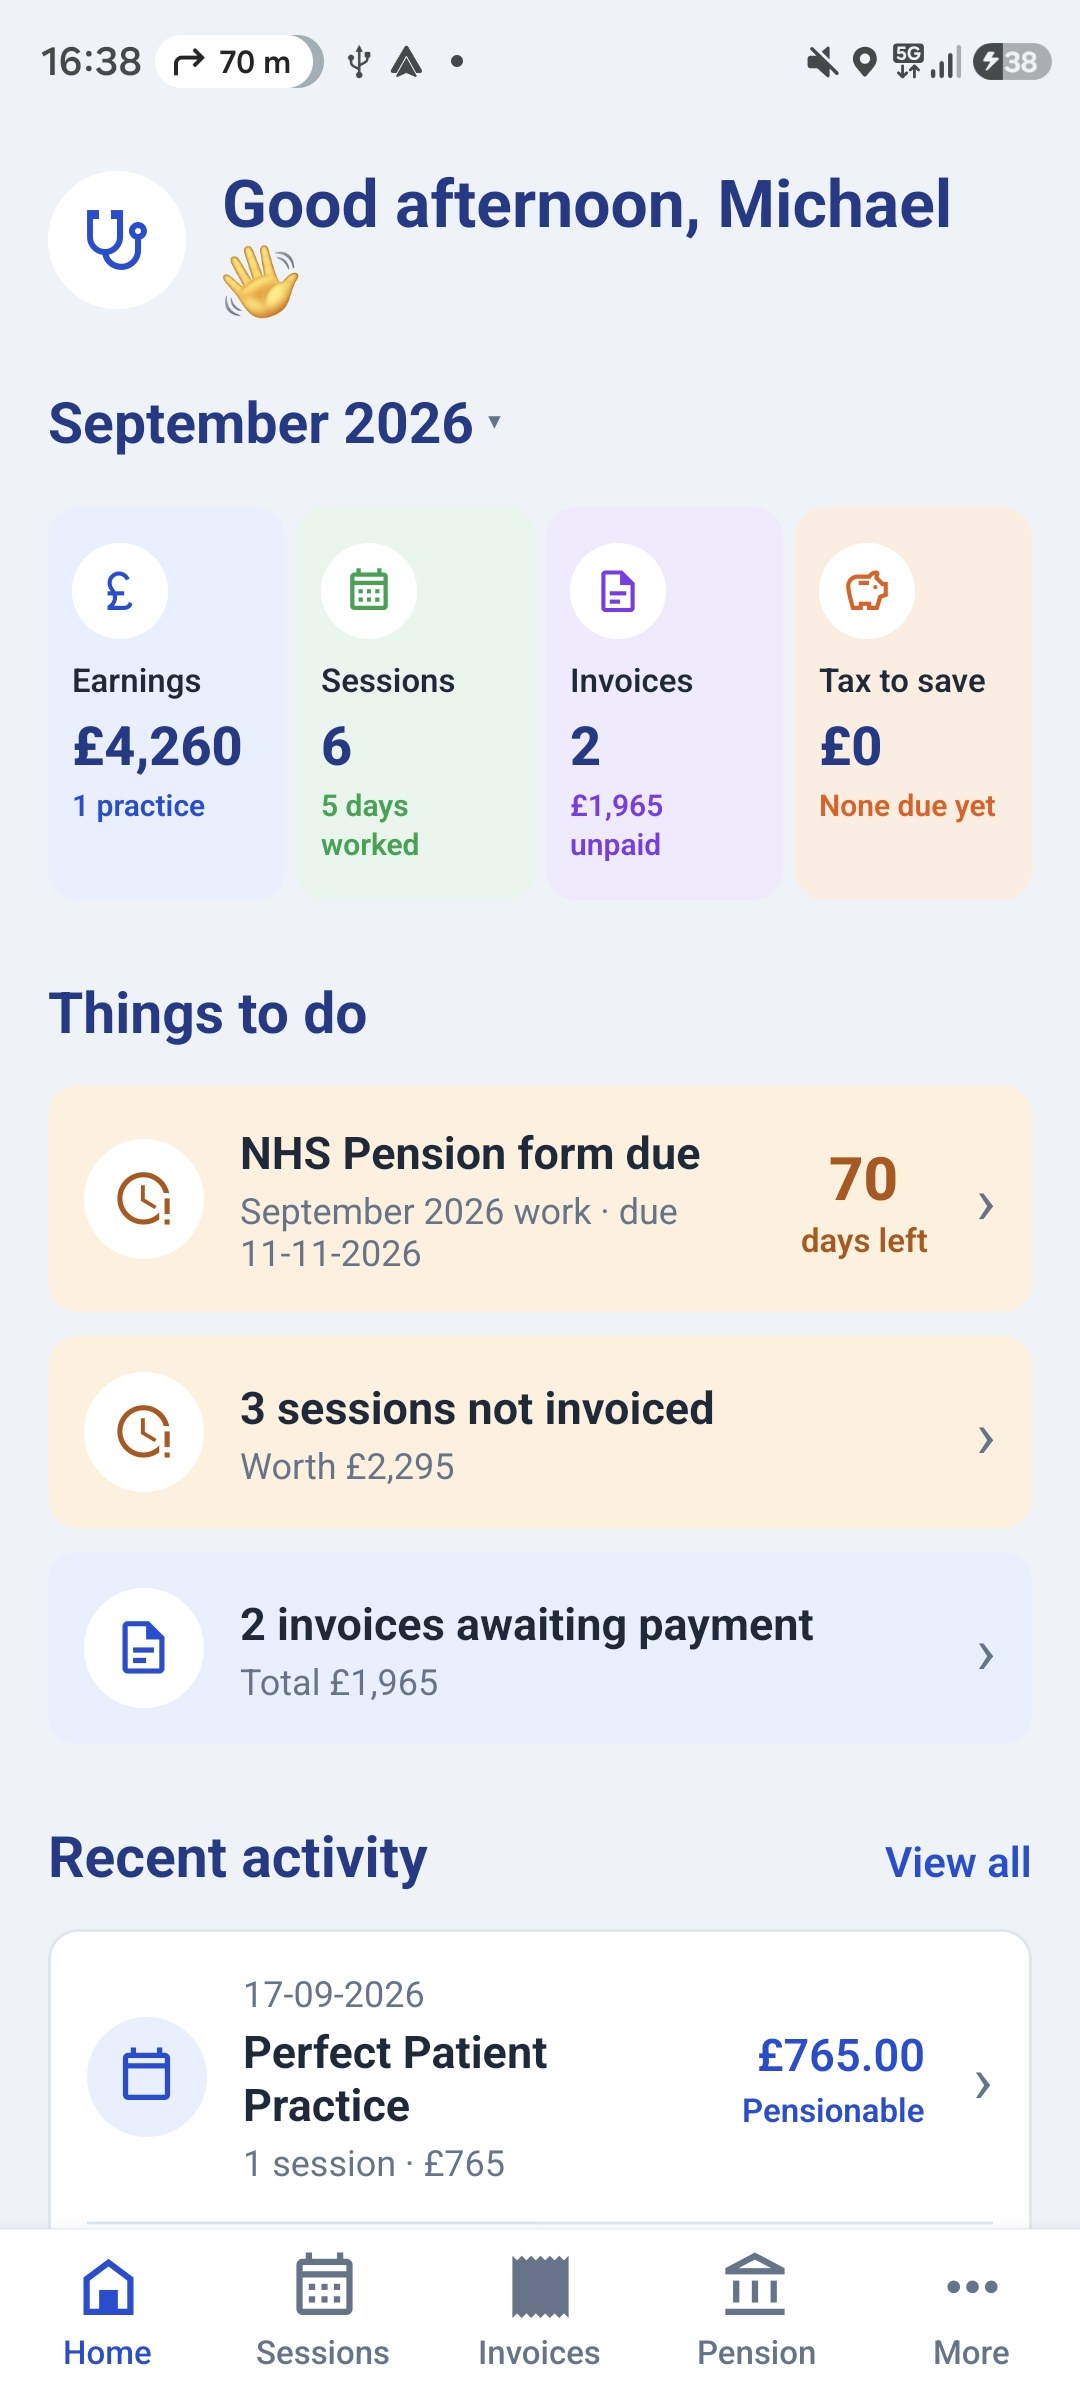
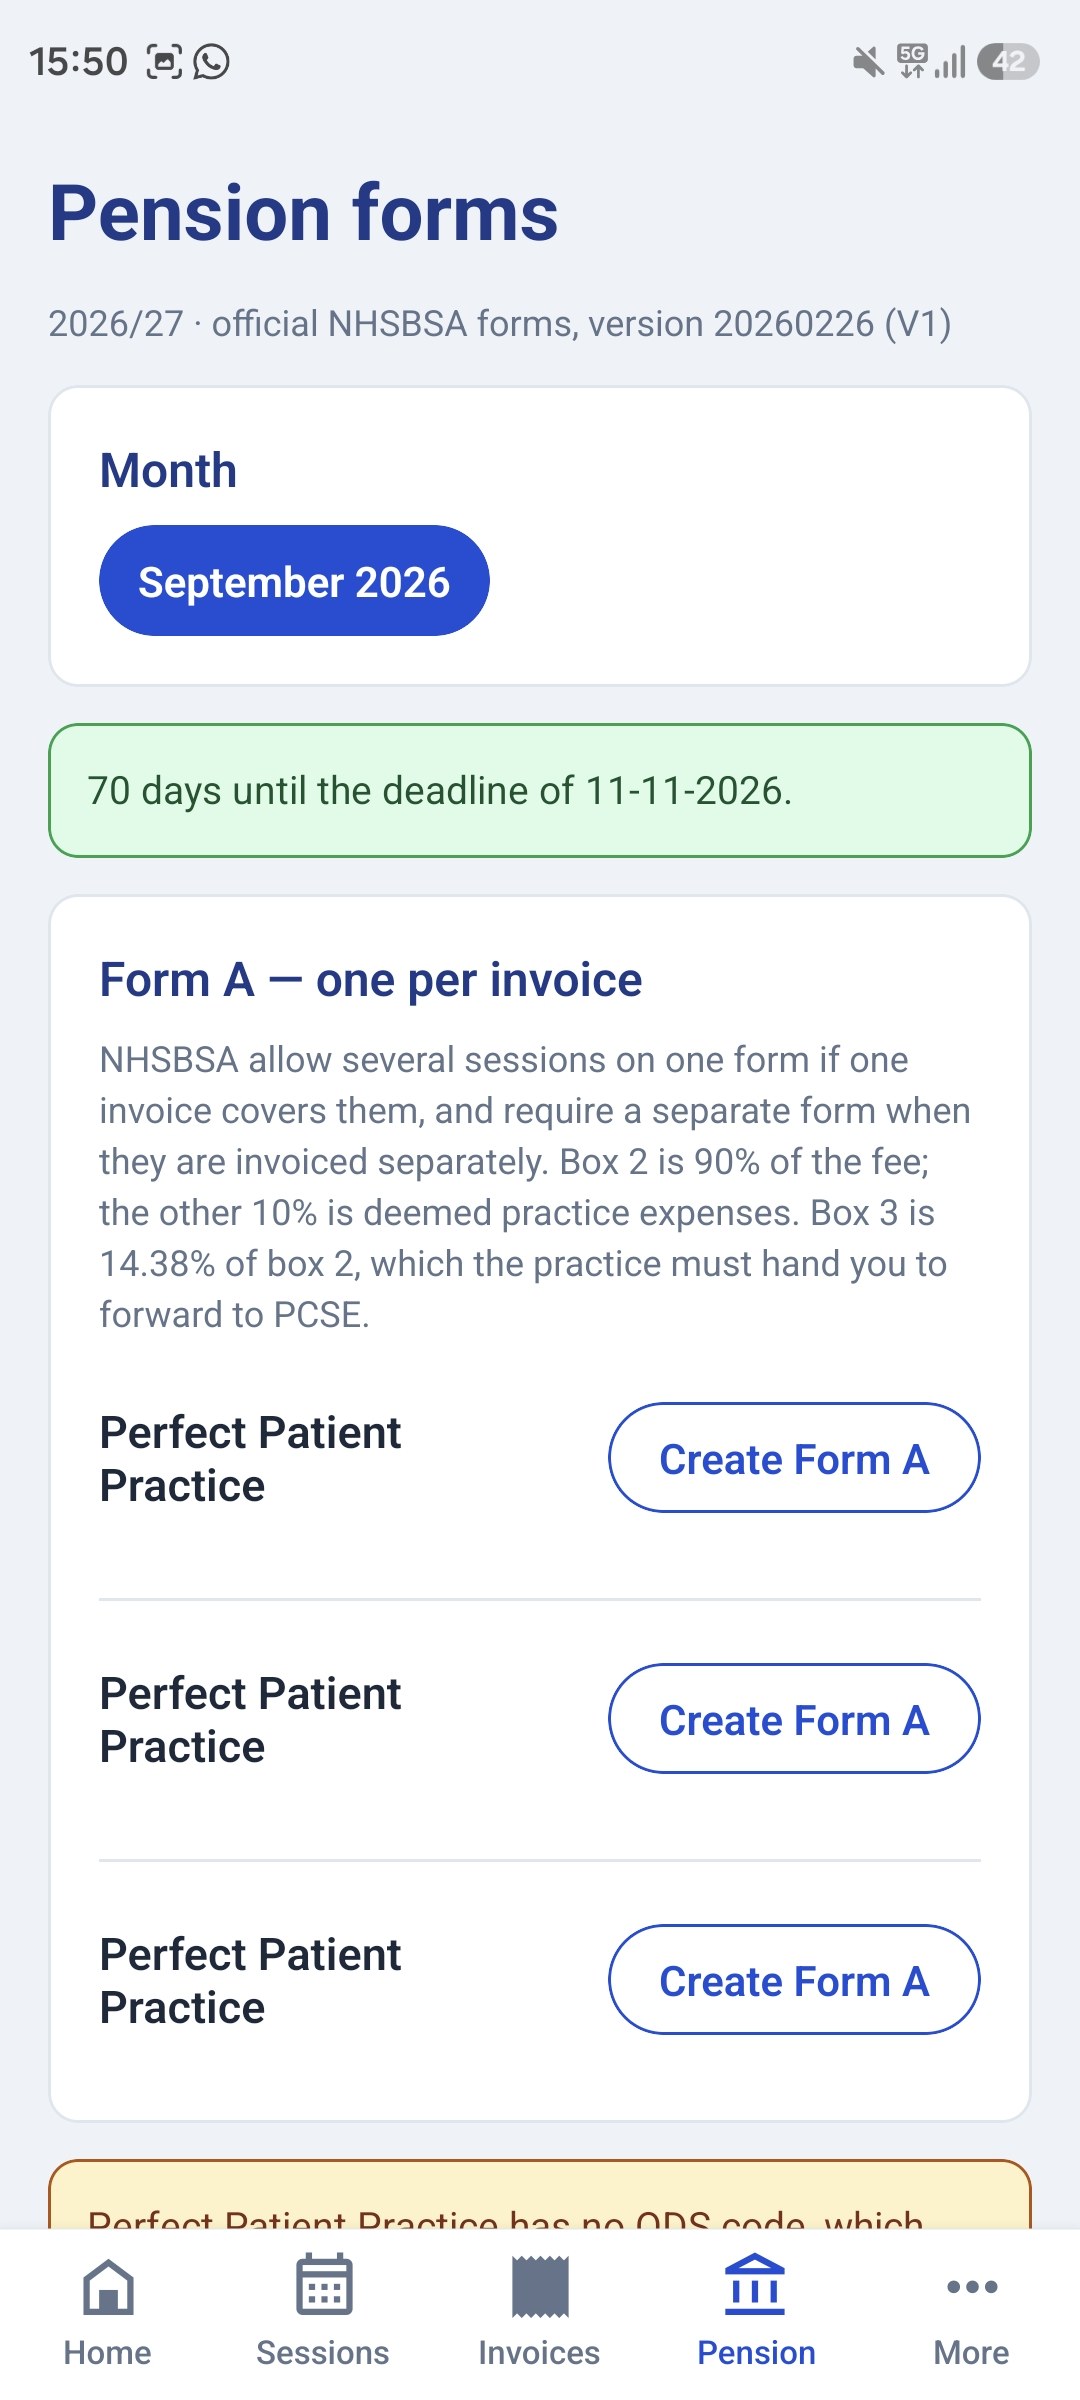
GP Locum fills the NHSBSA Form A and Form B from the sessions you log, works out the contributions, and keeps the 10-week deadline in front of you, so the locum work you pension actually reaches your record. On your phone and on the website.
Transfer values: what the CETV is for
A cash equivalent transfer value (CETV) is NHS Pensions' valuation of your benefits as a lump sum, for the purpose of a transfer. You are entitled to one free transfer value in any 12 months; further requests are charged for.
A CETV is used for divorce, where the courts need a value to share, and for the transfers that are permitted. It is not money you can take. It is also not the same as the hypothetical annuity cost on your Total Reward Statement, which is an estimate of what the same pension would cost to buy from an insurer.
Frequently asked questions
- Can I transfer my NHS pension to a SIPP?
- Not if you have two or more years' qualifying membership. Since 6 April 2015 NHS Pensions have not allowed transfers to SIPPs, personal pensions or any other scheme that provides flexible benefits. Members with less than two years' membership can transfer to a personal pension within strict time limits after leaving.
- Can I have a SIPP and an NHS pension at the same time?
- Yes. You can pay into a SIPP while staying in the NHS Pension Scheme. Tax relief on both is limited by your annual allowance, and the growth in your NHS pension counts towards that allowance as well as what you pay into the SIPP.
- Why can't the NHS pension be transferred to a SIPP?
- Because the NHS Pension Scheme is unfunded: there is no invested pot behind your benefits, which are paid from contributions and public money as they fall due. The Pension Schemes Act 2015 stopped members of unfunded public service schemes transferring to schemes where the money could be drawn flexibly as cash.
- Can I transfer my NHS pension after I leave the NHS?
- Only to another defined benefit scheme, or a scheme in the Public Sector Transfer Club, and the transfer must be completed before your normal pension age. You cannot transfer at all while you are still in NHS pensionable employment.
- What happens to my NHS pension if I opt out and pay into a SIPP instead?
- The pension you have already built up stays in the scheme as a deferred pension, increased each year in line with inflation and paid from your normal pension age. Only your future saving goes into the SIPP. You give up the NHS scheme's death in service, survivor and ill health benefits for the period you are out, and any employer contribution that would have been paid for you.
- Can I get a transfer value for my NHS pension?
- Yes. NHS Pensions will give you one cash equivalent transfer value free in any 12 months, and charge for more. While you are still working in the NHS it is only an estimate. It is the figure used for divorce and for permitted transfers, and it cannot be taken as cash.
Sources
Checked 4 October 2026. Where a primary source disagrees with anything here, the primary source wins.
- UK Transfer Out Guide and application pack, NHS Pensions, V15, December 2024: which schemes you can transfer to, the time limits, the £30,000 advice rule, and one free transfer value a year
- Leaving Early and Transferring Out Guide, NHS Pensions, V18A: deferred benefits and your options on leaving
- Pension Schemes Act 2015, legislation.gov.uk: the restriction on transfers from unfunded public service schemes
- Tax on your private pension contributions: annual allowance, GOV.UK
A note on advice
This guide is general information, not financial advice. Opting out of the NHS Pension Scheme gives up guaranteed, inflation-linked benefits and is hard to reverse. Get your own figures from NHS Pensions and consider an independent financial adviser who knows the NHS scheme before you decide.
Try the calculators
NHS Pension vs SIPP
Compare the NHS 2015 CARE pension with investing the same contributions in a SIPP, income, break-even return, and death benefits.
Open tool →NHS Pension vs SIPP
How the 2015 CARE pension and a SIPP compare: the employer contribution, break-even return, death and survivor benefits, and tax. Facts, not advice.
Read guide →Annual Allowance Calculator
Work out your annual allowance charge. The taper with its workings shown, carry forward, the band-by-band charge, Scheme Pays and the tax return boxes.
Open tool →What Is the Hypothetical Annuity Cost?
The big number on your Total Reward Statement: what it measures, why it is so large, and why it is not a transfer value.
Read guide →Know when these figures change
The rates here go out of date every April. Leave your email and I'll keep you updated on changes to these figures for the new tax year and any related GP finance news, pensions, tax and locum money. Unsubscribe any time.